Commission operations ·
Insurance Commission Reconciliation for Small Agencies: A Lean Monthly Workflow
By SplitVerde editorial team · Insurance agency operations
You don't need a ten-person finance department to find missing commissions. You need a process that still works when the owner is busy selling policies.
The takeaway
Compare transactions rather than totals, preserve the original carrier evidence, and keep projected, reported, and paid amounts distinct.
Four ingredients, no unnecessary complexity
Keep original carrier statements, a list of expected commissions, transaction-level comparison results, and an exception log. Choose a consistent monthly review date aligned with statement cycles. Resist building a sprawling workbook before you can explain a single policy payment.
Before making a conclusion, preserve the carrier's original statement and the period it covers. Validate the number of imported transaction rows and the signed commission total against the source. If the file is a PDF, inspect a sample of extracted policy references and amounts; if it is a spreadsheet, check leading zeros and date formats. A clean-looking table can contain bad data. Keep the source file alongside the working results so the next reviewer can trace any discrepancy without reconstructing the download. When the carrier revises a statement, store the revision separately rather than overwriting the earlier evidence.
A focused intake routine
Check which carrier statements arrived and mark missing periods. Validate row counts, signed totals, and sample policy references. PDF extraction and spreadsheet formatting can both introduce errors. An upload that succeeds technically may still produce inaccurate rows. Catch source problems before opening false shortage cases.
An expected commission is only as reliable as the assumptions behind it. Record the applicable carrier schedule, transaction type, commission basis, and eligibility conditions. A policy effective date does not automatically establish when commission becomes payable. Premium processing and statement cutoffs may matter. Mark uncertainty openly rather than assigning a confident due date that the contract does not support. Keep projected commissions, statement-reported commissions, and actual bank deposits separate. Those figures answer different questions, and collapsing them into one column creates avoidable confusion when the agency is planning cash flow.
Review material differences first
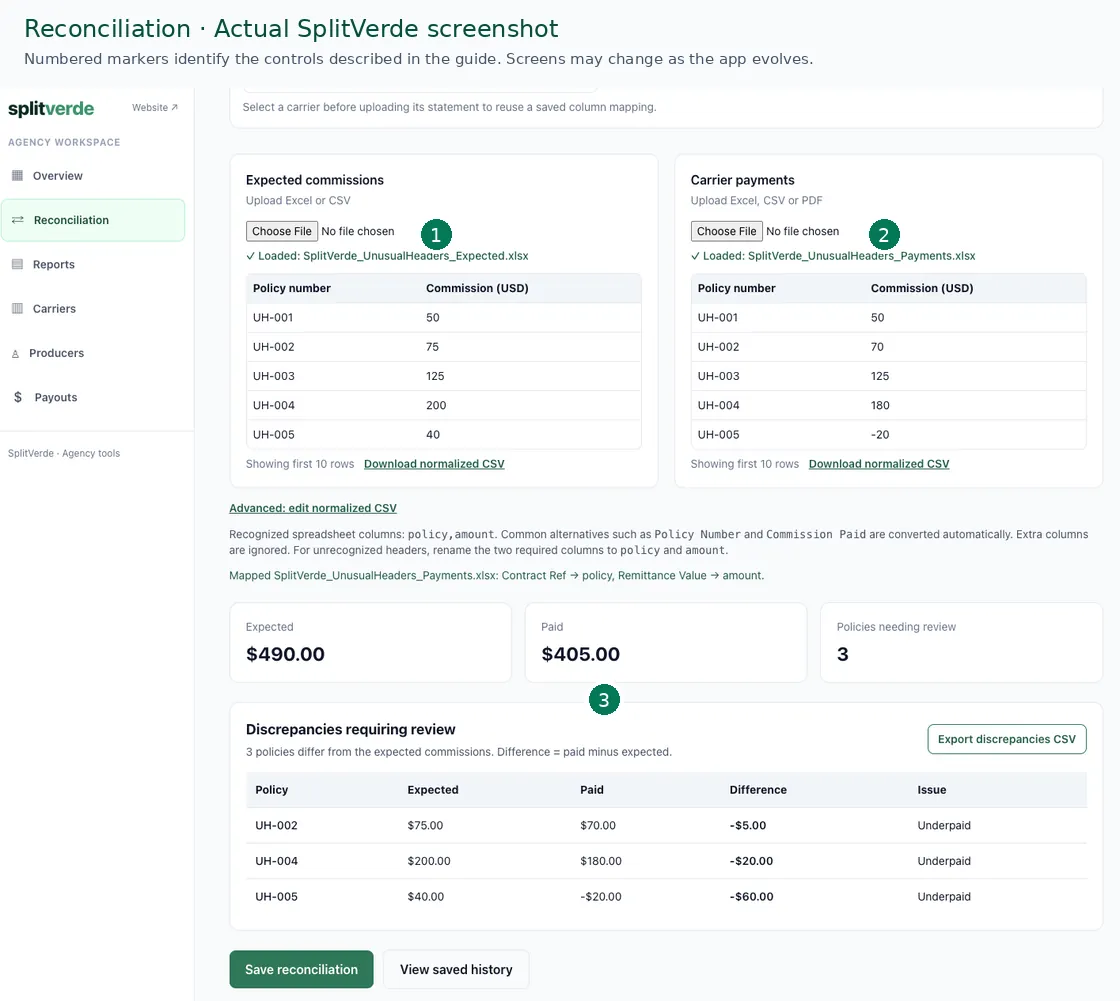
Compare expected and reported transactions by policy, type, and period. Sort confirmed shortages by amount and age. Keep timing questions separate. Two policies expected at $200 each can appear at $250 and $150; matching totals do not mean the underlying commissions are correct.
Transaction-level matching matters because totals can hide offsetting errors. Suppose Policy A is expected to pay $200 and Policy B is expected to pay $200. The carrier reports $250 on A and $150 on B. Both totals are $400, but each policy has a $50 discrepancy. Review carrier, policy reference, transaction type, statement period, and signed amount. Do not force an ambiguous match merely because two names or dollar values look similar. If an adjustment arrives later, retain the original transaction and add the new event. This preserves the timeline that makes future questions answerable.
| Policy | Expected | Carrier | Variance |
|---|---|---|---|
| A | $200 | $250 | +$50 |
| B | $200 | $150 | −$50 |
| Total | $400 | $400 | Two exceptions |
Fictional values; investigate policy-level differences rather than netting them away.
Use one shared exception queue
Record the carrier, policy, statement period, expected and reported amounts, suspected cause, owner, status, and next review date. Even a solo owner benefits from written follow-up. Leave promised corrections open until a later statement verifies them.
Every unresolved difference needs an owner and a next step. An exception log should include the source row, expected and reported amounts, signed variance, likely reason, status, and follow-up date. Separate confirmed shortages from transactions not yet due, unexpected positive commissions, duplicate candidates, and chargebacks. When contacting a carrier, send a focused inquiry with the policy reference, statement period, and basis for the expected amount. Save the reply. A promise that a correction will appear next month is not a verified resolution. Keep the issue open until a later statement supports closure.
Don't bypass producer checks
If the agency has producers, apply the correct agreement and split basis after reviewing carrier commission. Distinguish calculated, approved, and paid amounts. A carrier reversal does not automatically justify a producer deduction. If the agency has no producers, skip that step rather than adding needless complexity.
Producer compensation should be reviewed as a separate calculation. The agency's carrier commission is not automatically the amount payable to a producer. New-business and renewal rates may differ, and shared accounts may have special arrangements. Record the governing agreement version, commission basis, split rate, calculated share, and approval. A carrier chargeback does not automatically authorize a producer deduction; check the agreement and applicable law. Also distinguish calculated, approved, and actually paid amounts. A payout report is not proof that a bank transfer occurred, even when the arithmetic is correct.
Close the month without hiding problems
Save statements, validation totals, matched and unmatched results, open exceptions, and approvals. Reconcile bank deposits separately. Carry unresolved cases forward with their original evidence. Note one recurring bottleneck to improve next month. A simple workflow should reduce detective work, not erase uncertainty.
At month-end, keep a compact record of source statements, import validation, matches, open exceptions, carrier correspondence, and any producer approvals. Compare carrier remittances with bank deposits separately from policy-level matching. Assign unresolved cases to the next review period without rewriting earlier history. Ask whether someone unfamiliar with a transaction could find its source, calculation, and outcome in a few minutes. If not, improve the references. A reliable process is not one that makes every status green; it is one that exposes uncertainty and shows who is responsible for resolving it.
Frequently asked questions
Does a matching monthly total prove every commission is correct?
No. Offsetting policy-level differences can hide behind a matching grand total. Review individual transactions.
Is an expected commission the same as money in the bank?
No. Expected, carrier-reported, and deposited amounts are different checkpoints.
Can a chargeback automatically reduce a producer payout?
Not necessarily. Check the producer agreement and applicable law before changing compensation.
Related guides
Continue with our commission reconciliation guide, monthly checklist, and producer payout walkthrough.