Reconciliation ·
How to Build an Insurance Commission Discrepancy Report
By SplitVerde editorial team · Insurance agency operations
Practical insurance commission discrepancy report guidance for independent insurance agencies, with examples, controls, and a repeatable workflow.
The takeaway
Preserve the original carrier evidence, investigate differences at the transaction level, and distinguish expected, reported, approved, and paid amounts.
Match policy transactions
Start with the carrier statement itself. Keep the original download, reporting period, carrier name, and date retrieved. A transformed CSV or cleaned workbook may be easier to work with, but it should never replace the original evidence. Carrier portals sometimes change layouts or issue revisions, so keep both versions when that happens. Confirm the row count and signed total before importing. If the statement is missing entirely, flag the carrier period as incomplete instead of opening a separate missing-payment case for every policy. This simple distinction makes the exception queue much more useful. The goal is to preserve what the carrier actually reported, rather than a reconstructed version that nobody can independently verify.
Choose actionable columns
An expected commission is a calculation grounded in a policy, a transaction type, and a compensation schedule. Record the source of that expectation, including any effective dates or conditions. Do not assume that policy inception means the commission must be paid immediately. Premium processing and carrier statement cycles can affect timing. Keep expected, reported, and deposited amounts in separate fields. A number on a carrier statement is not necessarily a bank deposit, and a projected renewal is not proof of earned commission. When an assumption changes, record the new basis rather than silently overwriting the previous estimate. That history helps distinguish a genuine shortage from an outdated agency expectation.
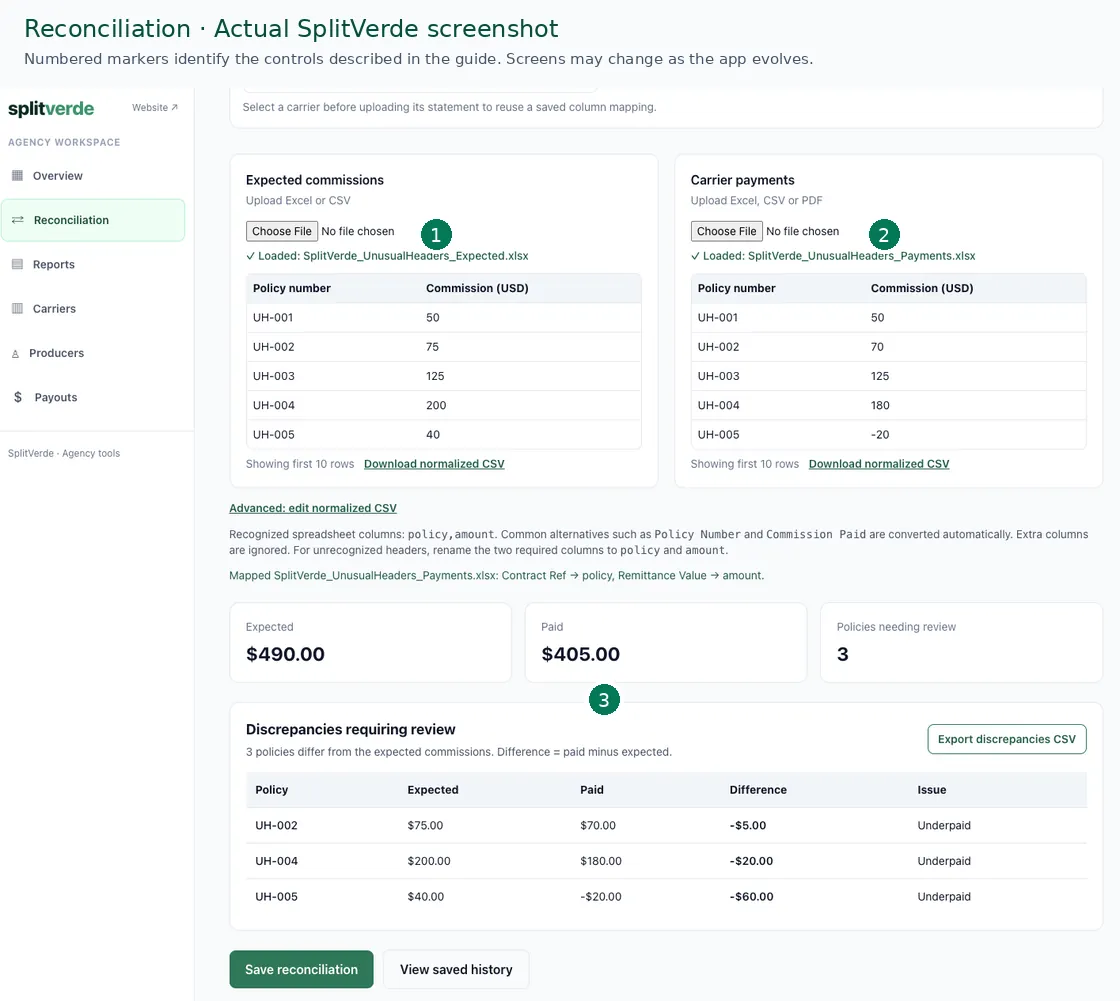
A discrepancy report should answer four questions at a glance: which transaction differs, by how much, why might it differ, and who owns the next step. Keep a source-row reference for every exception. Otherwise reviewers must search the entire carrier statement again. Make status values specific: awaiting agency research, awaiting carrier response, correction promised, correction verified, or not yet due. This is far more informative than a single generic error label. Avoid combining timing questions with confirmed shortages; the financial risk and next action are not the same.
Classify the differences
Match transactions by carrier, policy reference, transaction type, reporting period, and amount. Be careful with leading zeros in policy identifiers: spreadsheet software can strip them when a column is treated as numeric. A matching monthly total is not sufficient evidence. Suppose the agency expects $200 each on Policies A and B. The carrier reports $250 on A and $150 on B. Both totals are $400, yet each policy has a $50 discrepancy. Keep ambiguous matches in review instead of forcing them together based only on similar names or amounts. Negative transactions also need their own records. A chargeback should not erase the earlier positive payment simply because the resulting net looks tidy.
| Policy | Expected | Reported | Difference |
|---|---|---|---|
| A | $200 | $250 | +$50 |
| B | $200 | $150 | −$50 |
| Total | $400 | $400 | Two exceptions |
Fictional amounts; totals alone cannot verify policy-level accuracy.
Prioritize confirmed shortages
Create an exception log that tells the next person exactly what to do. Include the policy reference, source statement, expected amount, reported amount, signed difference, likely cause, owner, current status, and follow-up date. Separate missing payments, underpayments, unexpected positives, chargebacks, duplicate candidates, and timing questions. These cases require different investigations. Prioritize older confirmed shortages and material dollar differences, while keeping smaller anomalies visible. When contacting the carrier, reference the relevant statement period and transaction. Record the response. A carrier representative promising to correct a payment next month is progress, but it is not proof that the correction was made. Verify it against a later statement before closing the case.
Investigate offsetting errors
Producer compensation adds another layer and deserves its own checks. The commission reported by the carrier belongs to the agency-level reconciliation; a producer's share depends on the governing agreement, applicable split basis, transaction type, and effective date. New business and renewal splits may differ. Shared accounts may have more than one producer. A negative carrier adjustment does not automatically authorize a producer deduction: review the agreement and applicable law. Keep the calculated producer amount, approval status, and actual payment confirmation distinct. An exported payout report does not prove money was transferred. If the carrier corrects an older payment, show the producer adjustment clearly instead of silently rewriting an earlier statement.
Consider a report showing a $50 shortage on one policy and a $50 overage on another. The total difference is zero, but the exceptions remain real until explained. Do not net them away. Review the policy references, transaction types, and carrier periods. When a later correction appears, link it to the original exception and record the verification date. If the agency expectation was wrong, document the corrected rate or policy evidence. The report should preserve the history of that decision.
Verify corrections before closing
Close the period only after validating source totals, reviewing unresolved cases, and assigning follow-up dates. Compare the carrier's remittance against the bank deposit as a separate cash-control step. A deposit that matches the carrier's net statement amount does not prove every underlying policy commission was correct. Preserve the source files, exception explanations, correspondence, and payout approvals in a way another employee can follow. Try reconstructing a randomly selected older transaction without relying on anyone's memory. Can you find the original commission, later adjustments, calculation, and final decision? If not, improve the references. A useful system makes uncertainty visible, not invisible behind a reassuring green status indicator.
Frequently asked questions
Does a matching monthly total prove every commission is correct?
No. Different policy-level errors can offset each other. Compare the individual transactions.
Is an expected commission the same as a bank deposit?
No. Expected, statement-reported, and deposited amounts are separate checkpoints.
Can a chargeback automatically be deducted from a producer?
Not necessarily. Check the producer agreement and applicable law before changing compensation.
Keep learning
Read our reconciliation guide, monthly checklist, and producer payout guide.